[pageLogInLogOut]

#Raw Materials

Cotton market fundamentals & price outlook

Cotton Inc. recently published its May monthly economic letter on the fundamentals and price outlook of the cotton market. It reports that the trend in benchmark cotton prices was mixed last month. For example, the NY/ICE contracts continued to swing back and forth within the confines of their recent price ranges. The report also includes details of the USDA's first full estimates of supply and demand for the coming crop year, published in May.

Movement in benchmark cotton prices was mixed over the past month.

• NY/ICE contracts continued their pattern of swinging back and forth within the limits of their recent ranges. After climbing over 85 cents/lb in mid-April, the July futures contract collapsed to values below 80 cents/lb before the end of the month. Prices rallied in early May to 84 cents/lb before once again dropping below 80 cents/lb and then recovering to reach the current values near 81 cents/lb.

• Prices for the December figures contract (reflective of market expectations after the onset of the 2023/24 harvest) followed a similar pattern. Current values are also near 81 cents/lb.

• The A Index decreased and partially recovered over the past month. Values began the period near 96 cents/lb, fell as low as 91 cents/lb, and then climbed to 93 cents/lb.

• Chinese prices, represented by the China Cotton Index (CC 3128B), increased. Prices rose from 102 to 107 cents/lb between early April and May. In domestic terms, prices rose from 15,000 to 16,300 RMB/ton. The RMB weakened against the dollar, from 6.88 to 6.94 RMB/USD.

• Indian spot prices (Shankar-6 quality) eased from 97 to 94 cents/lb over the past month. In domestic terms, prices decreased from 63,000 to 60,700 INR/candy. The INR was steady against the dollar, holding near 82 INR/USD.

• Pakistani prices were near 82 cents/lb one month ago but traded above 85 cents/lb for most of the past month. More recently, prices have fallen back to 82 cents/lb. In domestic terms, prices held near 20,000 PKR/maund for most of the past month. The Pakistani rupee weakened from 285 to 295 PKR/USD from early April to early May.


Supply, Demand, & Trade

In May, the USDA issues its first complete set of supply and demand estimates for an upcoming crop year. For 2023/24, the USDA forecasts a slight 664,000 bale decrease in production (from 116.4 million in 2022/23 to 115.7 million in 2023/24) and a large 6.6 million bale increase in global mill-use (from 109.6 million in 2022/23 to 116.2 million in 2023/24). With world production and consumption nearly in balance, global ending stocks are expected to be nearly unchanged in the new crop year (-335,000, from 92.6 million bales for 2022/23 to 92.3 million in 2023/24).

At the country-level, the largest year-over-year changes in production are forecast for China (-3.2 million bales, from 30.7 in 2022/23 to 27.5 million in 2023/24), Turkey (-1.4 million, from 4.9 to 3.5 million in 2023/24), India (+1.0 million, from 24.5 to 25.5 million in 2023/24), the U.S. (+1.0 million, from 14.5 to 15.5 million in 2023/24), and Pakistan (+1.4 million, from 3.9 to 5.3 million in 2023/24).

The largest year-over-year changes in mill-use are expected from India (+1.5 million bales, from 23.0 in 2022/23 to 24.5 million in 2023/24), China (+1.0 million, from 36.5 to 37.5 million), and Pakistan (+1.0 million, from 8.6 to 9.6 million).

Global cotton trade is projected to expand by 5.0 million bales next crop year to 42.8 million. In terms of imports, the largest changes are expected from China (+2.2 million, from 6.8 to 9.0 million), Bangladesh (+1.1 million, from 6.9 to 8.0 million), and Vietnam (+600,000 bales, from 6.3 to 6.9 million). In terms of exports, the largest changes are forecast from Brazil (+1.8 million, from 6.9 to 8.7 million in 2023/24), India (+1.0 million, from 1.4 to 2.4 million in 2023/24), and the U.S. (+900,000, from 12.6 to 13.5 million).


Price Outlook

There has been renewed concern about 2022/23 production recently. The current focus of attention is India, where arrivals at gins are significantly behind the pace from one year ago. There has been speculation that Indian growers may be withholding volume in hopes of securing better prices, but the breadth of the gap has given root to worry that the Indian crop may end up being smaller than currently forecast.

As the situation unfolds, it should be remembered that cotton is a global commodity and that unfortunate conditions in one country can be balanced against favorable outcomes from other locations. At this point in the year, southern hemisphere growers have started harvesting. Expectations are that Australia and Brazil will collect near-record harvests, and those crops will soon be physically available.

In the meantime, it may be noteworthy that Indian cotton prices have been easing while production concerns have been mounting. One explanation is that lower supplies must still be balanced against demand. In the current demand environment, there may not be enough downstream pull to render supply tight, even if production in certain locations is lower than was previously hoped. The same phenomenon can be used to explain how prices managed to work their way lower with the Pakistani flood in October.

In the new crop year, demand may resurface. The global textile supply chain sharply pulled back on order volumes after the global surge in inflation and the series of increases in interest rates that followed. Whenever inventories stabilize, a recovery back to trend order volumes may support demand. However, any increases in inventory-related demand will have to be balanced against the macroeconomic situation.

The speed and magnitude of increases in interest rates worldwide may have yet to be fully digested by economies. Regardless of whether a recession is looming in major downstream markets, global economic growth is projected to be sluggish. The International Monetary Fund (IMF) is projecting world GDP to hover around three percent from 2024 through 2028. Global growth around these levels is not associated with strong growth in cotton mill-use. A persistently slow macroeconomic situation could impede a surge in demand like those that followed other recent economic downturns and contributed to the price volatility in 2010/11 and 2022/23.

Read the full Monthly Economic Letter: May 2023.

https://www.cottonworks.com/wp-content/uploads/2023/05/Monthly-Economic-Letter-May-2023.pdf


More News from TEXDATA International

#ITM 2026

ITM 2026: The new geography of textile production

New production hubs are emerging across North Africa and Central Asia, while Türkiye is accelerating its transformation toward higher-value, technology-driven and more sustainable textile manufacturing.

#Research & Development

“Production is a product”

From technical textiles and AI-driven robotics to the limitations of textile circularity: Professor Dr Thomas Gries looks back on more than two decades of development at ITA Aachen. In the interview, he explains why production technology remains a decisive success factor, discusses international collaborations and innovation ecosystems, and shares his views on the transformation of production landscapes and the challenges facing an increasingly regulated industry.

#Knitting & Hosiery

“We need to move away from the price trap and return to a value-driven mindset.”

With its new Textile Innovation Center, KARL MAYER is sending a strong signal for innovation, collaboration, and the future of textile applications. In this interview, Karl Josef Mayer discusses new opportunities in warp knitting, the processing of staple fibres, recycling, the changing role of machinery manufacturers, and why the textile industry must once again focus more strongly on the value of textiles. by Oliver Schmidt

#Associations

“Innovation, resilience and international experience remain the great strengths of the Swiss textile machinery industry”

Geopolitical uncertainty, growing competitive pressure from China, new free trade agreements and the shift towards a circular economy are currently reshaping the global textile industry. In this interview, Cornelia Buchwalder discusses the current mood within the Swiss textile machinery sector, the industry’s distinctive innovative strength, new market opportunities in India and Asia, and the technological trends that could shape the upcoming trade fair cycle leading up to ITMA 2027.

More News on Raw Materials

#Natural Fibers

ICAC announces 84th Plenary Meeting in Egypt with focus on cotton industry resilience

Registration is now open for the International Cotton Advisory Committee’s 84th Plenary Meeting, which will take place from 24 to 26 March 2027 in Alexandria, Egypt. The conference will address climate resilience, technological developments, sustainability and competitiveness across the global cotton and textile value chain.

#Raw Materials

New Cotton Review examines competitiveness, market risk, and opportunities

From moving record volumes of Brazilian cotton to market, to managing price volatility, unlocking Ethiopia’s production potential, and strengthening African textile trade, the latest edition of Cotton: Review of the World Situation examines some of the most consequential opportunities and challenges facing the global cotton industry.

#Raw Materials

Kraig Labs ships first commercial spider silk yarn

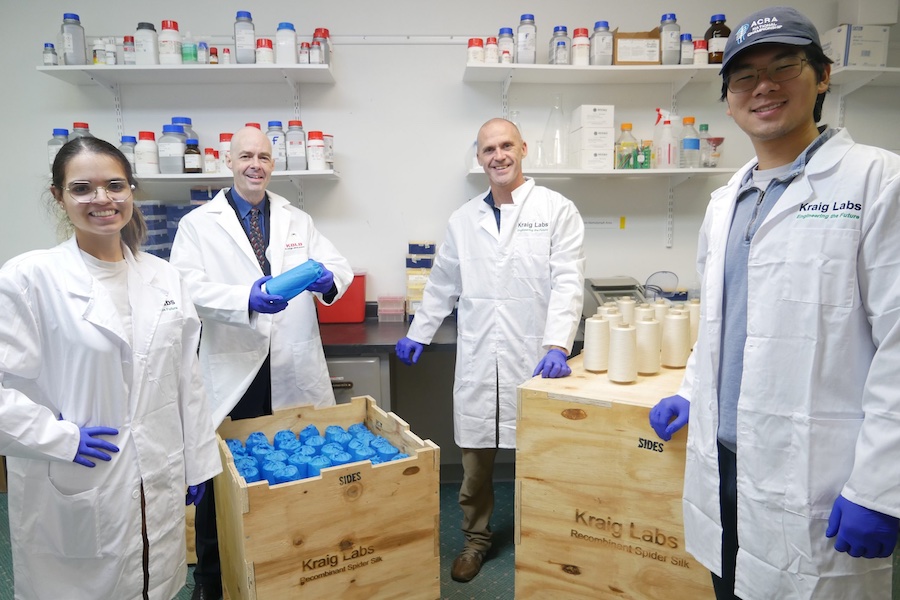
Kraig Biocraft Laboratories, Inc. (OTCQB: KBLB) (“the Company”, “Kraig Labs”, or “Kraig’s”), a world leader in spider silk technology*, today announced the shipment of its first commercial order of recombinant spider silk yarn. The custom-engineered yarn was produced to fulfill a purchase commitment from a globally recognized performance sports brand and is slated for development into a first-of-its-kind performance textile.

#Raw Materials

ALLIED expands down traceability with lot-level carbon footprint data

ALLIED Feather + Down has expanded its TrackMyDown traceability platform to include validated cradle-to-gate carbon footprint data linked to individual down lots. The initiative is designed to provide brands and consumers with more detailed environmental information on the materials used in finished products and could also support future data requirements associated with Digital Product Passports.

Latest News

#ITMA Asia + CITME 2026

Groz-Beckert to present innovations across six textile technology sectors at ITMA Asia 2026

From November 20 to 24, 2026, Groz-Beckert will be presenting its highlights and innovations across the various product areas – Knitting, Weaving, Nonwovens, Sewing, Tufting and Spinning – in Hall 4.1, Booth D41 at the ITMA ASIA + CITME 2026.

#ITMA Asia + CITME 2026

Vandewiele to showcase weaving innovations and automation solutions at ITMA Asia 2026

At ITMA ASIA + CITME 2026, taking place from November 20 to 24 in Shanghai, Vandewiele will present a broad range of technologies for weaving, carpet manufacturing, tufting, yarn processing and automation. The company's innovations focus on increasing productivity, improving process efficiency, reducing resource consumption and providing greater flexibility in textile manufacturing. Visitors can explore the latest developments at Booth D01 in Hall 3 of the National Exhibition and Convention Center (NECC).

#ITMA Asia + CITME 2026

KARL MAYER expands TM WEFT capabilities for fashion fabrics at ITMA ASIA 2026

A new E 36 gauge, an EL pattern drive and improved yarn tension regulation extend the application possibilities of KARL MAYER's TM WEFT warp knitting machine. At ITMA ASIA 2026, the company will demonstrate the developments alongside a collection of woven-like warp knitted fabrics for fashion and apparel.

#Recycling / Circular Economy

Textiles Recycling Expo USA 2027 opens registration and expands with manufacturing exhibition

The second edition of Textiles Recycling Expo USA will take place on 7–8 April 2027 in Charlotte, North Carolina. Following a debut that attracted more than 1,800 visitors and 95 exhibitors, the event will expand its exhibition and conference programme and will be held alongside the new Textiles Manufacturing Expo.

TOP