#Market Analysis & Forecasts
Fluff pulp market maintains steady growth
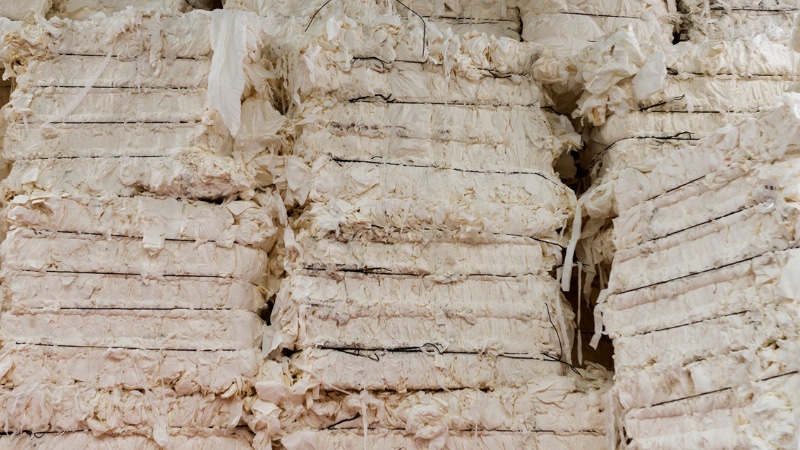
Fluff pulp consumption is forecast by the business intelligence firm to reach 8.6 million air dried tonnes valued at $11.5 billion by 2029. Compound annual growth rates are 3.3% (volume) and 11.9% (value) for 2019-24 and are projected at 3.4% (volume) and 3.6% (value) for 2024-29.
These projections show the fluff pulp market has maintained moderate volume and value growth amidst being jolted by geopolitical issues like the Russia/Ukraine war, Israel/Hamas War, and Houthi aggression in the Red Sea. Economically, China’s economic slowdown is slowing overall market penetration there as the percentage of consumers able to afford fluff pulp containing products falls.
Produced from coarse, long fibre softwoods, fluff pulp historically has been a specialty pulp grade with higher prices and margins than the more common papermaking pulp grades. Accounting for 9-10% of the total pulp market globally in 2024, the normal pricing for fluff pulp for the last 42 years has shown a cyclicality that has high and low points every 2-6 years.
End-uses for fluff pulp centre on the absorbent core for hygiene products, including the large global diaper/nappies, feminine hygiene, and adult incontinence markets, as well as nonwovens.
Nonwovens, while only accounting for about 8.4% of the fluff pulp market, are growing at an over 4% per year rate. One major reason for this change is the global megatrend towards reducing plastics in nonwovens and other end-uses. While airlaid and coform nonwovens use are somewhat capacity constrained, fluff pulp use in spunlace is forecast to continue to grow much more rapidly than other fluff pulp uses.
Business landscape
After several years of relative stability (other than price), the global fluff pulp market has entered a very active phase. By 2029, either fluff pulp supply will be very tight or there will be unannounced expansion. Additional South American expansion and/or re-opening of some closed lines in North America are possibilities.
Regional production and consumption
The regional markets of North America and South America are the only major exporting regions for fluff pulp in 2024. North America will export over 80% of the fluff pulp it produces, and South America will export nearly 35% of its fluff pulp in 2024. In 2024, North America accounts for almost 80% of all fluff pulp produced globally and South America adds another 12%; the Americas combined produce almost 92% of the global fluff pulp supply.
All other geographic regions are net importers. South America had the largest fluff pulp capacity increases for 2019-24, increasing capacity by 92%, with expansions from Klabin, Suzano and Arauco. While the expansions seem to have slowed for 2024-29, South America is still projected to add almost 50% more fluff pulp production.
In consumption, Asia is the largest volume region, and is projected (for 2024-29) to resume its position as the fastest growing region. Western Europe is the second largest consumer of fluff pulp in volume and value from 2019-29. North America is third in consumption.
More info:
https://www.smithers.com/services/market-reports/nonwovens/the-future-of-fluff-pulp-to-2029